Debt consolidation is the process of combining multiple debts into a single repayment arrangement, usually with one monthly payment. Instead of managing several credit card balances, personal loans, or other eligible debts separately, a person may use a consolidation loan or another method to combine them into one payment.
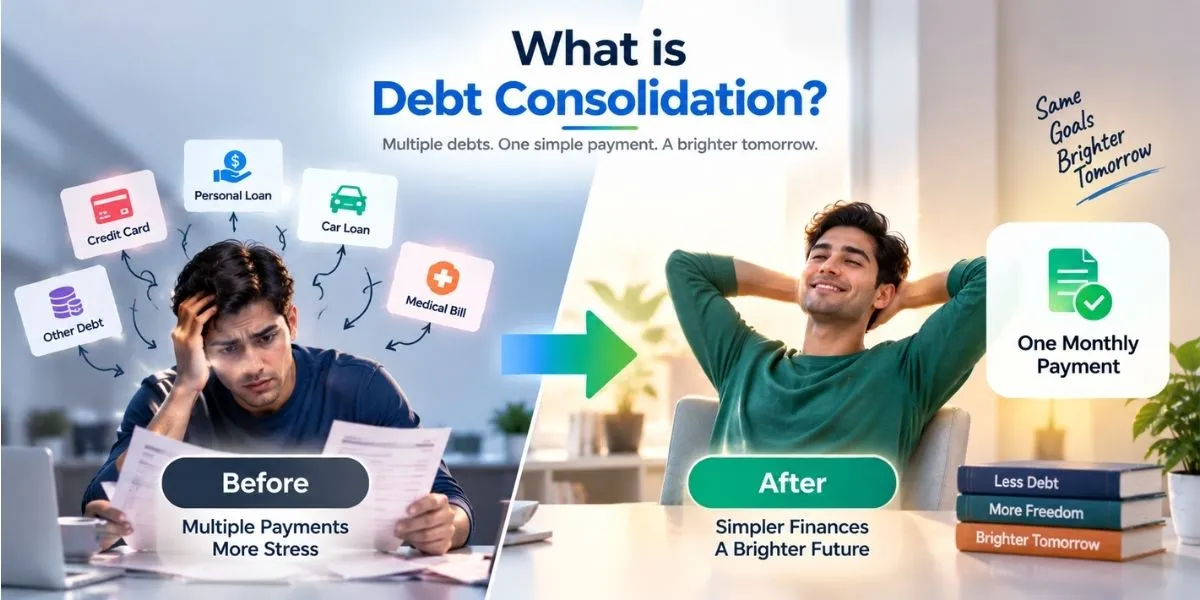
In simple terms, debt consolidation can make multiple debts easier to manage, but it does not make the debt disappear. Whether consolidation saves money depends on factors such as the interest rate, fees, repayment period, and terms of the new arrangement.
How Does Debt Consolidation Work?
Suppose you have several debts with different interest rates, balances, and payment dates. A debt consolidation loan may be used to pay off some or all of those debts. You then make payments toward the new loan instead of making separate payments on the original debts.
Another option can be a balance transfer, in which eligible credit card debt is moved to another credit card, often under specific promotional terms.
The important thing is to compare the total cost of the new arrangement, rather than looking only at the new monthly payment.
How Can Debt Consolidation Help?
Debt consolidation may provide several potential benefits:
1. Simplifies Monthly Payments
Instead of keeping track of multiple due dates and payments, consolidation may leave you with one scheduled payment, making debt management simpler.
2. May Lower the Interest Rate
If the new arrangement has a lower interest rate than your existing debts, you may pay less interest. However, promotional rates can expire, and fees may affect the overall savings.
3. Makes Budgeting Easier
A single scheduled payment can make it easier to organize your monthly budget and track your debt repayment.
4. Provides a Defined Repayment Period
A consolidation loan may have a fixed repayment schedule, allowing you to estimate when the debt could be fully repaid if payments are made as agreed.
Does Debt Consolidation Get Rid of Debt?
No. Debt consolidation generally reorganizes debt rather than eliminating it. You still have to repay the amount owed, along with any applicable interest and fees.
If overspending or an unbalanced budget contributed to the debt, taking out another loan without addressing those issues may leave you with continued financial difficulties. Before consolidating, it can be helpful to review your budget and understand why the debt accumulated.
What Are the Risks of Debt Consolidation?
Debt consolidation is not automatically cheaper. A longer repayment period may reduce the monthly payment but increase the total interest paid over the life of the debt. Origination fees, transfer fees, or other charges can also increase the total cost.
Some consolidation methods may involve secured debt, meaning an asset can serve as collateral. Missing payments on a secured loan can put that asset at risk.
What Should You Check Before Consolidating?
Before choosing debt consolidation, compare:
Interest rate and whether it can change
Loan or transfer fees
Total repayment amount
Repayment period
Whether collateral is required
Monthly payment and affordability
Any promotional-rate expiration dates
Whether you have addressed the cause of the original debt
A nonprofit credit counselor may also help you understand different debt-management options.
Conclusion
Debt consolidation combines multiple debts into one repayment arrangement and may make payments simpler or reduce interest costs in some situations. However, it does not erase debt, and a lower monthly payment does not necessarily mean a lower total cost.
Before consolidating, compare the interest rate, fees, repayment period, and total amount you will repay to determine whether the new arrangement fits your financial situation.
Also Read: What is Dizziness